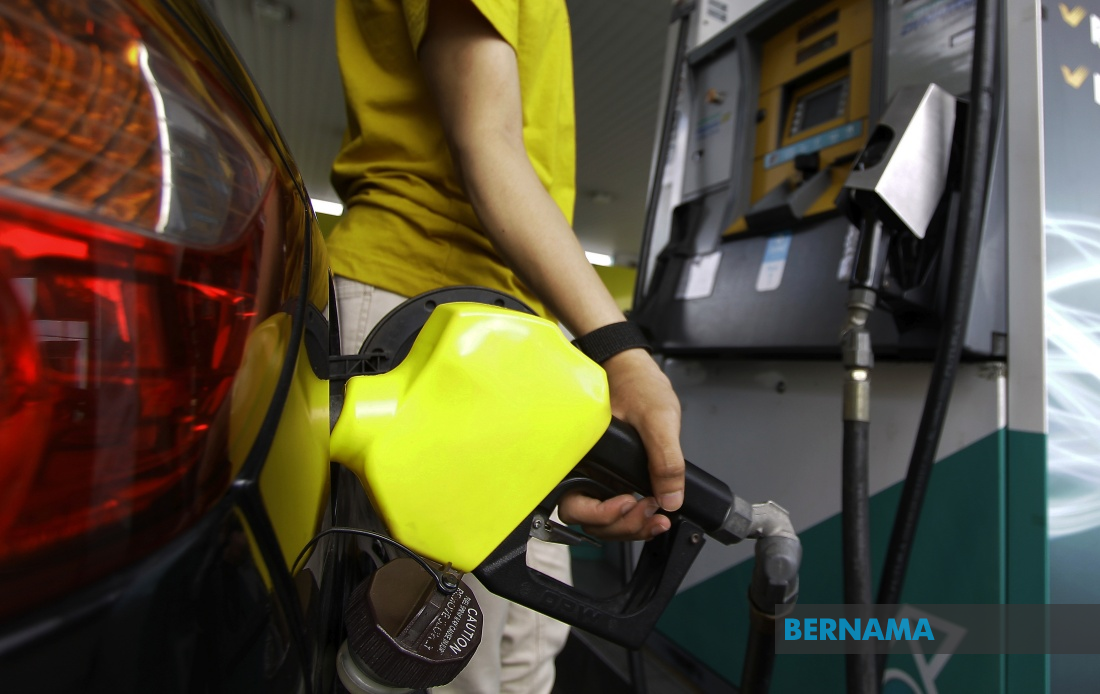
Kenanga Research said it is turning cautious on mid-market retailers in the consumer segment and have decided to cut their valuation basis for departmental store and apparel players from 15-fold to 12-fold, at a 20 per cent discount to the segment’s average historical forward price earnings ratio (PER) of 15-fold. – Bernama Photo
KUCHING (Sept 27): A large part of the M40 group may be ‘cut off’ from the impending targeted fuel subsidy and cause the group to encounter diminished disposal income moving forward, said the Kenanga Investment Bank Bhd’s research arm (Kenanga Research).
In a sector update report, the research arm guided that the upcoming targeted fuel subsidy which will be unveiled during the tabling of Budget 2024 on October 13 is expected to replace the existing blanket fuel subsidy and will likely come into full effect at the start of 2024.
The creation of the new targeted fuel subsidy is largely motivated by the unsustainable financial burden of the current existing blanket fuel subsidy setup, where a considerable 35 per cent of the RM77.3 billion subsidy in 2022 was utilised for fuel subsidies that benefitted the wealthier T20 group.
“Leveraging the new Central Data System (PADU) database that integrates data from various government agencies including the Inland Revenue Board (LHDN) and the Road Transport Department (JPJ), the government aims to identify recipients using a ‘net disposable income’ criterion, intending to largely exclude the T20 demographic,” the research arm detailed.
Despite its best intentions, the research arm believed that a large part of the M40 group will likely still be inadvertently excluded from the new fuel subsidy, which might result in lower disposable income and reduced spending power for the group.
As such, the research arm said it is turning cautious on mid-market retailers in the consumer segment and have decided to cut their valuation basis for departmental store and apparel players from 15-fold to 12-fold, at a 20 per cent discount to the segment’s average historical forward price earnings ratio (PER) of 15-fold.
However, it remains positive on consumer staples players as their target customers, the B40 group will continue to fully enjoy subsidised fuel and not encounter erosion to the group’s spending power.
“In addition, the group will continue to receive financial assistance from the government including cash handouts,” it added.
Furthermore, consumer staples players are also anticipated to enjoy some respite from recovering margins as prices of certain soft commodities have been easing in recent months, these include milk, wheat, and corn which have seen prices decline as much as 10 to 30 per cent year to date (YTD).
However, the prices of sugar and cocoa have surged more than 30 per cent YTD due to adverse weather conditions that have impacted beet crop and cocoa production.
All in, the research arm maintained its valuation basis for consumer staples players at 22-fold, which is in line with the segment’s average forward PER.
Meanwhile, Kenanga Research anticipated an overall slowdown in consumer spending as the MIER Consumer Sentiment Index (CSI) demonstrated a declining trend for two consecutive quarters, dropping below the pivotal 100-point mark.
“This trend indicates that the consumer populace is adopting a more cautious spending stance, influenced by escalating inflationary pressures and augmented interest rates,” the research arm explained.
“Concurrently, the Retail Group Malaysia (RGM) has revised their annual growth forecast for the CY23 retail industry downwards to 2.7 per cent, a decrease from the previous 4.8 per cent, following a disappointing second quarter of 2023 (2Q23) performance with a -4.0 per cent growth rate,” it added.
Kenanga Research revised its 2023 consumption projection downward from 6.1 per cent growth to 4.1 per cent, as well as downgrading their previous ‘overweight’ stance on the consumer sector to ‘neutral’.